About Debt Payoff Planner & Tracker
I’ve tried a few budgeting apps before, but they always felt like they were built for someone else’s finances. When I downloaded the Debt Payoff Planner & Tracker, I was just hoping to get a clearer picture of my $8,000 in credit card debt. What I got was a tool that felt like it was built for my specific, slightly panicked, situation. It didn’t just list my debts—it gave me a plan I could actually stick to.
Features & Highlights
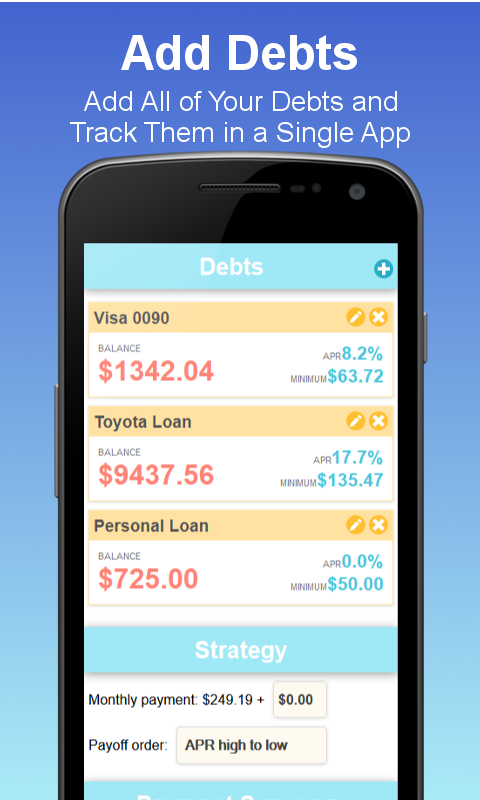
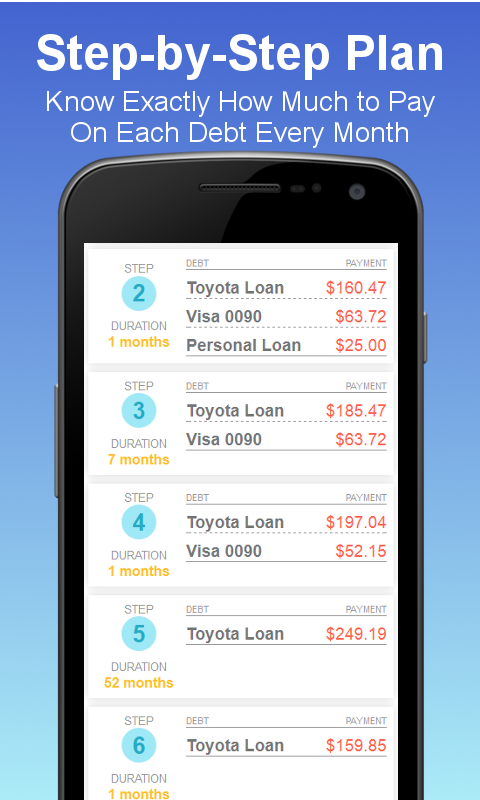
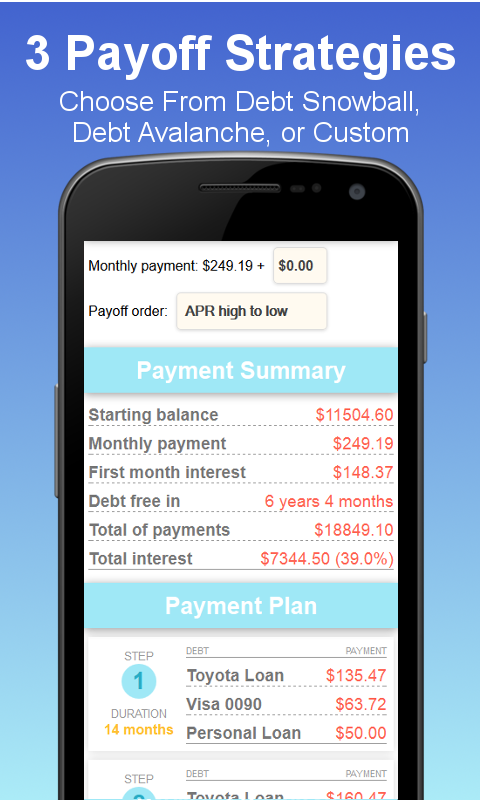
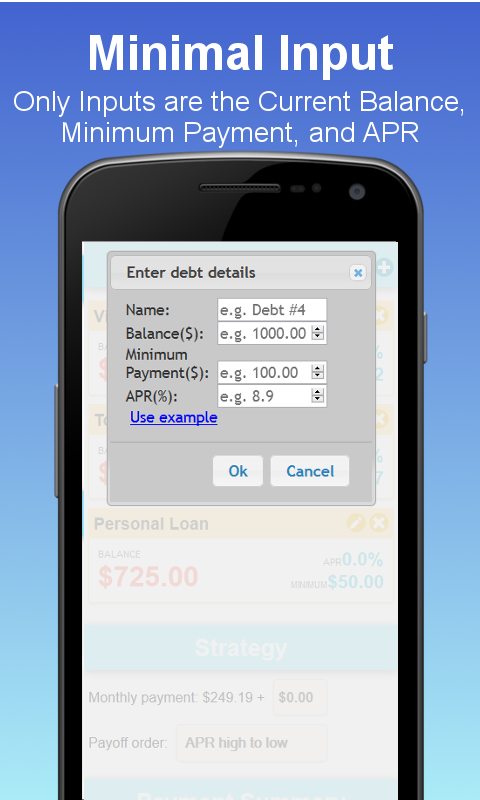
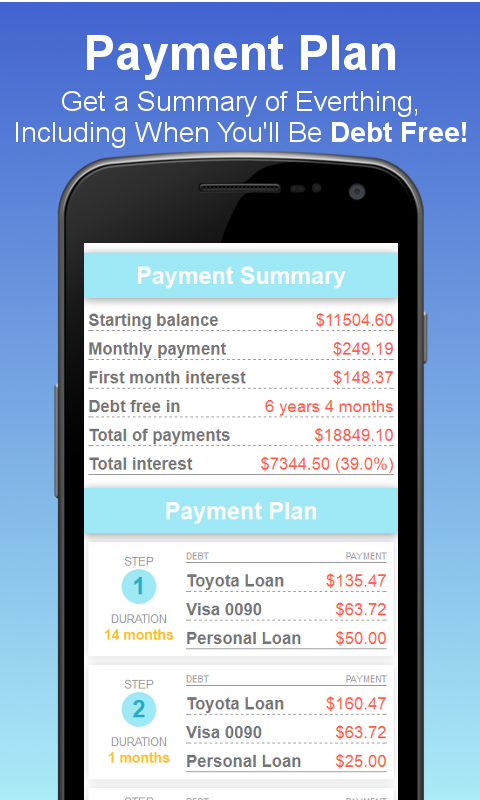
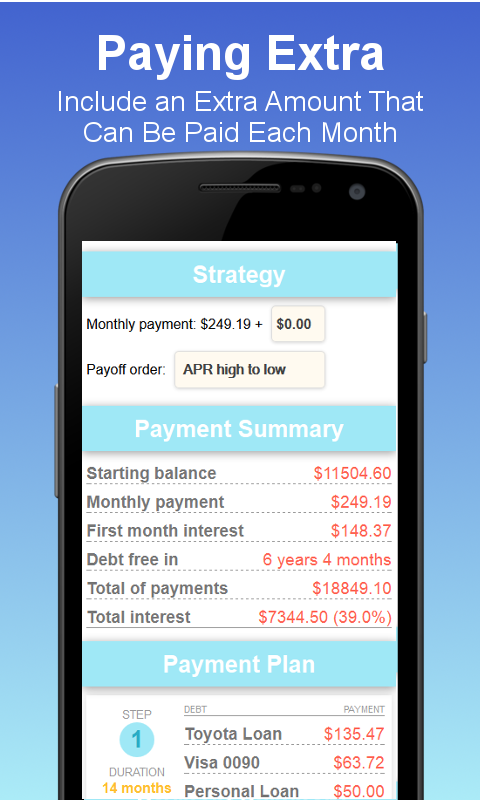
The dashboard is the first thing you see, and it’s a game-changer. Instead of a scary total number, it showed me my projected debt-free date right at the top. I could add each of my three credit cards with their different interest rates and minimums. The feature I used most was the payoff strategy comparison. I could toggle between the debt snowball (paying off smallest balances first) and the avalanche (targeting high interest). Seeing the timeline and total interest difference for each method on a simple chart made my decision easy. I went with the avalanche, and the app automatically prioritized my payments. Setting up payment reminders for each card’s due date finally stopped me from getting those annoying late fees.
User Experience
My favorite moment was after my first month of using the plan. I logged a payment that was $50 over the minimum, and the app instantly updated my dashboard. Seeing my debt-free date move up by 18 days was a tiny, tangible victory that kept me going. The interface is clean and doesn’t bombard you with complicated graphs. Entering a payment takes two taps, which is crucial because if it’s a hassle, I won’t do it. I did have to look up what “avalanche method” meant the first time, but the in-app explanation was clear enough. It feels designed for someone who needs guidance, not a finance expert.
Pricing
The app is free to download and use for its core functions. I’ve been using the free version for three months and haven’t hit a paywall for anything essential like adding debts, setting strategies, or tracking payments. There is a premium version that unlocks extra features like data export and more detailed reports, but for my goal of just getting out of debt, the free tier has been completely sufficient. It’s absolutely worth downloading.
Updates & Support
I get an update notification every few weeks, usually for minor bug fixes or performance improvements. The app feels stable. I had one question about whether a car loan should be listed as an “installment” or “other” debt, so I used the contact form in the app’s settings. I got a helpful, non-automated reply from a person named Sam within 48 hours, which was better than I expected for a free app.
Security & Privacy
I downloaded this directly from the official Google Play Store. The best part is that the app works completely offline; you don’t even need to create an account. All my debt data stays on my phone. I never had to link a bank account or provide any personal financial details. There are small banner ads at the bottom of the screen in the free version, but they’re static and not intrusive video ads. The privacy policy is straightforward—since it doesn’t collect data, there’s not much to share or sell.
How does the app help me choose between the debt snowball and avalanche methods?
The app lets you toggle between both strategies and shows a simple chart comparing your payoff timeline and total interest for each method. This makes it easy to see which approach saves you more money or gets you out of debt faster, so you can pick the one that fits your goals.
Can I set up payment reminders for each of my credit cards?
Yes, you can set individual payment reminders for every debt you add, based on each card's due date. This helps you avoid late fees and keeps you on track without having to remember multiple dates.
What should I do if I don't understand a term like 'avalanche method' in the app?
The app includes clear in-app explanations for financial terms like the avalanche method. If you're ever unsure, just tap on the term or look for a small info icon next to it for a brief, easy-to-understand definition.
Why isn't my debt-free date updating after I log a payment?
Make sure you're logging a payment that is at least the minimum amount due. The app instantly recalculates your debt-free date when you enter a payment, especially if you pay more than the minimum—it should update immediately on your dashboard.
How does Debt Payoff Planner & Tracker compare to a general budgeting app like Mint?
While Mint focuses on overall budgeting and tracking all your accounts, this app is specifically designed for paying down debt with features like payoff strategy comparisons and a projected debt-free date. It gives you a step-by-step plan tailored to your debts, which Mint lacks.