First Impression
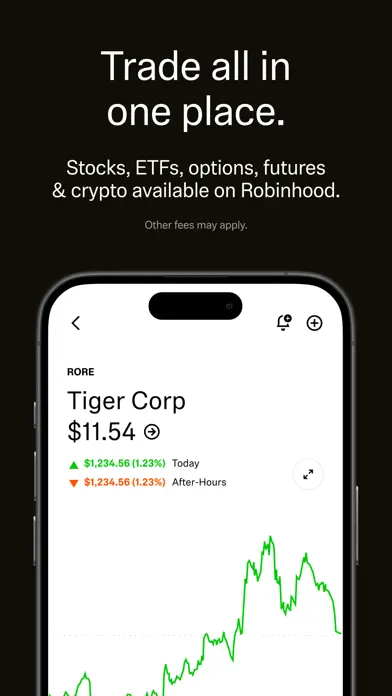
Last Saturday morning, I was sitting at the kitchen table with my coffee, scrolling through my phone, when my 12-year-old daughter asked if we could buy stock in the company that makes her favorite video game. I’d always thought investing was something for people with fancy laptops and financial advisors. Tom, my brother-in-law, had been talking about Robinhood for months at family dinners, saying it was “stupid simple.” So I finally downloaded it. The setup took maybe 10 minutes. It asked for my ID, linked my bank account, and within a few hours I could start trading. No confusing jargon, no paperwork on my desk. The app looked clean and modern, not like something from 2005. I honestly expected it to be harder. My first real moment was that Saturday afternoon when I bought two shares of Disney for my daughter. She was thrilled. I was nervous but also proud that I could actually do it without messing something up.
What It Does Well
The biggest thing Robinhood gets right is keeping things simple. I’m not someone who reads stock charts for fun. I don’t know what a moving average is. But I can open the app, see a list of popular stocks, tap on one, and read a plain-English summary of what the company does. Buying and selling feels like ordering a pizza. You tap a button, choose how many shares, and hit confirm. That’s it. No hidden fees, which honestly blew my mind. I remember calling my bank once to buy a mutual fund and they wanted a $50 fee. Here, it’s free every time. The recurring investment feature is huge for me. I set up a weekly $20 buy for an S&P 500 fund. It happens automatically every Tuesday morning. I don’t think about it. Over the last few months, I’ve seen that little pile of money grow a bit. Not enough to retire on, but enough that I feel like I’m actually doing something smart for my family. The cash management thing is nice too. The money sitting in my account earns a little interest, which is better than my regular savings account. My daughter now has a little portfolio of three stocks she picked herself, and checking on it together has become a Sunday night routine. She learns about companies and saving, and I don’t feel lost.
Where It Falls Short
This app is not for serious traders. I’ve read about the outages and the payment-for-order-flow stuff, but honestly, it hasn’t affected me much. What bothers me more are the little things. Sometimes the real-time data feels delayed. I’ve watched a stock price stay frozen for a few seconds, then jump. That’s scary if you’re trying to sell something at a specific price. Also, the crypto part is way too tempting for beginners. My son saw Bitcoin going up and wanted to buy some. I let him with $10, and within two days he was down $2 and panicking. The app makes crypto feel like a game, not like real money. There’s no warning that says, “Hey, this is gambling more than investing.” Another thing: the customer service. When my bank transfer got stuck for five days, I contacted support through the app. A real person finally replied after three days. That’s a long time when your money is in limbo. The reply was helpful, but three days felt like forever. I’m not okay with that for an app that handles actual cash. Also, the news feed is full of clickbait. “This stock could triple by Friday!” type headlines. Not exactly educational for my kids.
Is It Worth the Price?
It’s free, so yes, it’s worth the price for what it is. There are no monthly fees, no commission on trades, no hidden costs I’ve found. But that doesn’t mean there’s no cost. You’re paying with your data and with the fact that your trades might not get the best price compared to a more expensive broker. I’ve read about how they sell order flow to big trading firms. That makes me uncomfortable, like I’m the product. For someone like me who buys and holds small amounts, the difference is probably pennies. But if you’re trading a lot, those pennies add up. I’d rather pay a small fee and know my trade got the same treatment as a Wall Street guy’s. Also, the app pushes you to upgrade to Robinhood Gold for retirement accounts and bigger deposits. I haven’t done it. For my simple needs, the free version works fine. Just don’t expect fancy research tools or hand-holding. This is a bare-bones way to buy stocks, and that’s exactly what I needed.
Developer & Support
I’ve only contacted support once, like I said, when my bank transfer got stuck. I filled out the in-app form on a Tuesday. I got an email back on Friday. That’s three business days. The email was polite and actually solved the problem—turned out my bank needed an extra verification step. So they fixed it, but waiting three days felt like an eternity when I couldn’t use the money I’d deposited. The app has a Help Center with FAQs, but most of them are generic. I wish there was a phone number. Even a callback system would be better than relying on emails. On the plus side, the app updates pretty often. I get notifications about new features or bug fixes. It feels like they’re maintaining it. But the lack of real-time human help is a dealbreaker for anyone who’s nervous about money. If you’re the type to panic and need answers in an hour, this might not be for you.
Privacy & Safety
This is my biggest concern as a parent. Robinhood asks for a lot of personal information: Social Security number, bank account details, driver’s license photo. That makes me nervous, but I guess it’s standard for a brokerage. They use two-factor authentication, which I recommend everyone turn on immediately. The app also stores your login biometrics if you let it, like fingerprint or face scan, which feels safer than typing a password on a public Wi-Fi. What I don’t like is how the app tracks your activity. I’ve noticed ads on other websites for stocks I searched in Robinhood. That’s creepy. They claim they don’t sell your personal data, but they definitely use it for marketing. For my kids, I made sure they can’t access the app without my face scan. I also set up a conversation with my daughter about never sharing her account info with anyone, even friends. The app has a security page that explains encryption and insurance (SIPC protects up to $500,000), which gave me some peace of mind. But I still check my transaction history every week. I’d rather be paranoid than lose money.
How do I set up recurring investments in Robinhood?
To set up recurring investments, go to the stock or fund you want to buy, tap the recurring icon, and choose your frequency (e.g., weekly) and amount. For example, you can schedule a $20 weekly buy for an S&P 500 fund, and it will automatically execute every Tuesday morning without any extra effort.
Can my child pick and manage their own stocks on Robinhood?
Yes, you can create a custodial account for your child, allowing them to choose stocks while you oversee the account. The app's simple interface makes it easy for kids to learn about investing, like picking three stocks and checking on them together as a weekly routine.
Why does the stock price sometimes freeze or feel delayed in Robinhood?
Robinhood's real-time data can occasionally lag, causing prices to appear frozen for a few seconds before jumping. This is a known limitation, especially during volatile trading, so avoid relying on it for time-sensitive trades and consider using limit orders instead.
What should I do if my crypto investment drops quickly and I'm panicking?
If your crypto investment drops, remember that crypto is highly volatile and can feel like gambling. Robinhood doesn't provide warnings, so it's best to start with small amounts you can afford to lose and avoid checking prices constantly to prevent emotional decisions.
How does Robinhood compare to using a traditional bank or broker for buying stocks?
Unlike traditional banks that charge fees like $50 per mutual fund trade, Robinhood offers commission-free trading with no hidden fees. However, it lacks advanced tools and customer support, making it better for casual investors than serious traders who need real-time data and personalized help.