About Lyft Direct powered by Payfare
I downloaded this app two weeks ago because I was sick of the financial lag. Driving for Lyft means your income is unpredictable, and waiting for the weekly bank transfer felt like being stuck in the past. My old bank would hold funds until Tuesday, but my car needs gas on Sunday. I needed my money to move as fast as I do. After seeing the high rating, I figured I’d give it a shot on my Galaxy S23, expecting it to be another half-baked fintech experiment. My initial thought was just to test the Instant Pay feature, but I ended up using it for almost everything.
Core Features
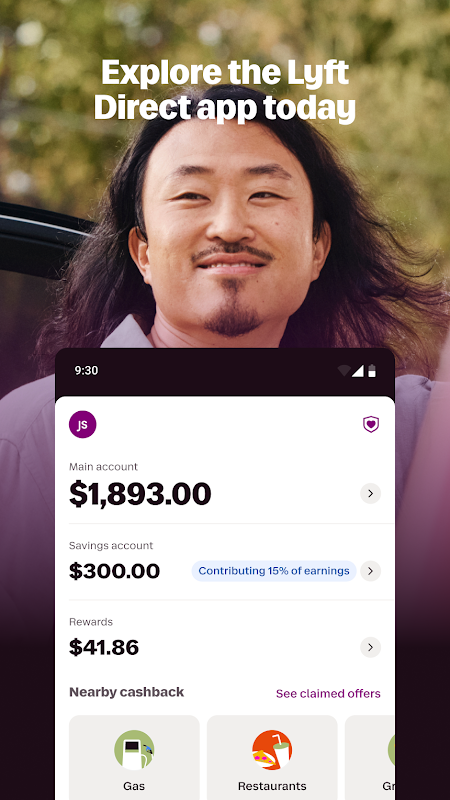
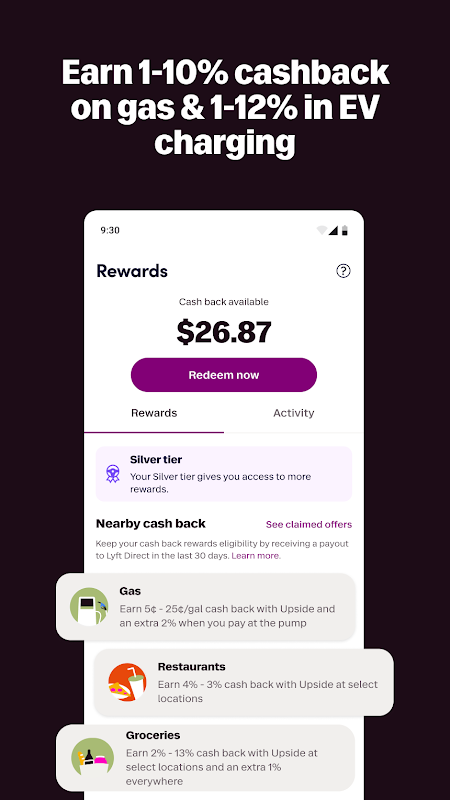
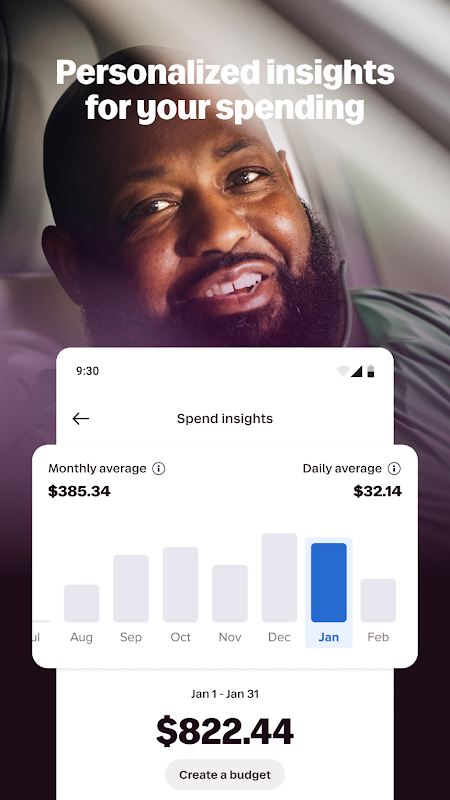
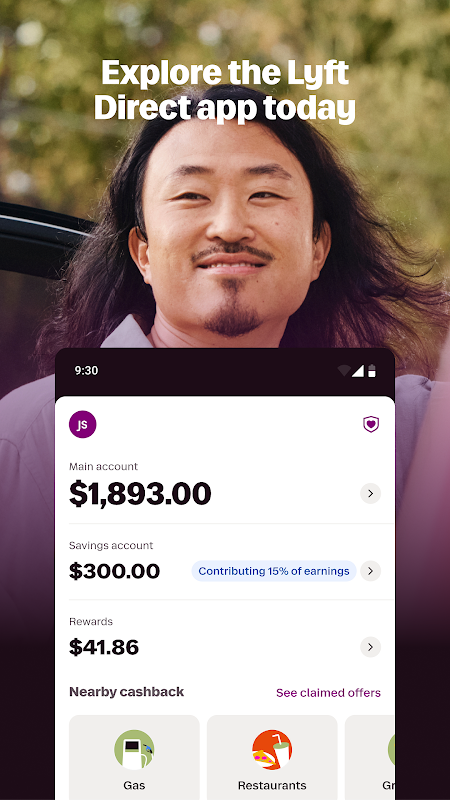
The instant access to earnings is the main draw, and it works exactly as advertised. The moment you tap “cash out” in the Lyft driver app, the money is in your Lyft Direct account. No waiting, no pending period. The card itself is a standard Visa debit card, but the fee-free ATM network through Allpoint is genuinely useful. I found machines at my local Walgreens and Target. The cashback rewards are a nice touch, especially the 2% back on gas—it’s a logical perk for drivers. There’s also a basic earnings tracker built in, which gives you a clearer picture of your weekly take than the Lyft app alone. It’s not a full accounting suite, but it’s better than nothing.
Real-World Use
This is where I put it through its paces. Last Thursday, I finished a long airport run at 10 PM. My phone was at 8% and I was on empty. Instead of stressing, I cashed out my last fare right in the airport cell lot, drove to the 7-Eleven down the road, used their Allpoint ATM for free cash to get a charger and a snack, then used the card at the pump. The whole process took ten minutes. That’s powerful. However, I hit a snag trying to pay my insurance bill online. The payment processor flagged the Lyft Direct card as a “prepaid card” and rejected it twice. I had to transfer the money to my traditional bank to complete the payment, which added a day of delay and defeated the purpose.
Pricing & Value
You can’t argue with free. No monthly fees, no minimum balance, free in-network ATM withdrawals. For a driver looking to avoid bank fees, it’s a no-brainer. The value is clear when you’re avoiding those $3 ATM charges at sketchy gas stations. The cashback is basically found money that offsets small costs. But “free” sometimes means you’re the product, or that certain features are missing. The value proposition crumbles if you need to do anything slightly advanced, like depositing a cash tip or setting up automated bill pay with certain companies. It’s great for spending, less great for managing.
Updates & Support
I haven’t needed to contact support personally, which is either a good sign or just luck. The app itself has updated once since I installed it, with vague patch notes about “performance improvements and bug fixes.” Scrolling through the app store reviews, you see a pattern. Most are glowing, but the one-star reviews are brutal—people locked out of their accounts for days with no help. That’s a red flag for me. An app that holds your earnings needs rock-solid, responsive support, and the negative feedback suggests it might not be. I’m keeping my balance low just in case.
Data & Privacy
This is my biggest lingering question. The app needs full access to your Lyft driver account to function. It sees every ride, every fare, every adjustment. Payfare’s privacy policy is a typical wall of legal text. They share data with partners for “business purposes.” I’m not overly paranoid, but I don’t like that my entire driving financial life—a precise map of my work habits and spending—is now in the hands of another company I know little about. They promise it’s secure, but in 2024, promises aren’t enough. I wish there was more transparency about what they do with the granular data they collect.
How does the instant access to earnings work with Lyft Direct?
When you tap 'cash out' in the Lyft driver app, the money instantly appears in your Lyft Direct account with no waiting or pending period. This lets you access your fares right after a ride, even late at night or on weekends.
What cashback rewards and fee-free ATM options are available?
The card offers 2% cashback on gas purchases, which is a practical perk for drivers, and you can use the Allpoint ATM network for free withdrawals at places like Walgreens and Target. There's also a basic earnings tracker in the app to help you monitor your weekly take.
Why was my Lyft Direct card rejected when trying to pay a bill online, and how can I fix it?
Some online payment processors flag the Lyft Direct card as a 'prepaid card' and may reject it. To fix this, transfer the money to your traditional bank account and then use that account to complete the payment.
Can I use the Lyft Direct card at any ATM without fees?
No, the card is fee-free only at ATMs within the Allpoint network, which includes locations at stores like Walgreens and Target. Using an out-of-network ATM will likely incur fees.
How does Lyft Direct compare to a traditional bank account for Lyft drivers?
Lyft Direct is much faster for accessing earnings—money lands instantly instead of waiting days for a bank transfer—but it may be rejected by some bill pay systems as a prepaid card. Traditional banks handle online payments more smoothly but don't offer instant cash-out.