My Experience with Beem: Better than Cash Advance
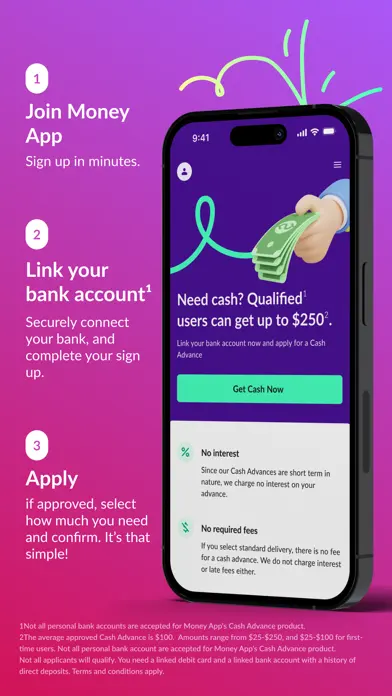
I got Beem because my cat, Milo, needed a last-minute vet visit on a Tuesday afternoon. My paycheck was still three days out, and I needed about $100 to cover the deposit. I’m usually very careful with my money, but this was a genuine pinch. The setup was fast—I linked my main checking account using Plaid on my iPhone 15 Pro. That’s where my first red flag went up. The permissions screen asked for access to read my bank transaction history, not just verify the account. I paused, read their privacy policy, and decided to proceed because I was stressed about Milo. After all that, the app approved me for a grand total of $20. For a vet bill, that was almost laughable. I contacted support, asking why the amount was so low. They got back to me a few days later (not the same day) and said it was based on my “banking activity.” They were polite and helpful, but the delay meant the moment had passed. I ended up putting the bill on a credit card. The whole point was to avoid that, so my three-day test felt pretty defeated from the start.
Features Worth Noting
The money, when you get it, does arrive quickly. After my initial $20 test, I requested it just to see the process. It hit my account in under two minutes, which is impressive. I like that they don’t do a hard credit pull. Protecting my credit score is important to me, so that’s a legitimate benefit. The interface is clean and simple, which makes navigating the basics easy. There’s also a “Beem It” feature for sending money to friends. I sent $15 to my roommate for pizza that same night, and it worked instantly with no fee. It feels like a separate app glued onto this one, but it functioned perfectly fine.
What Needs Work
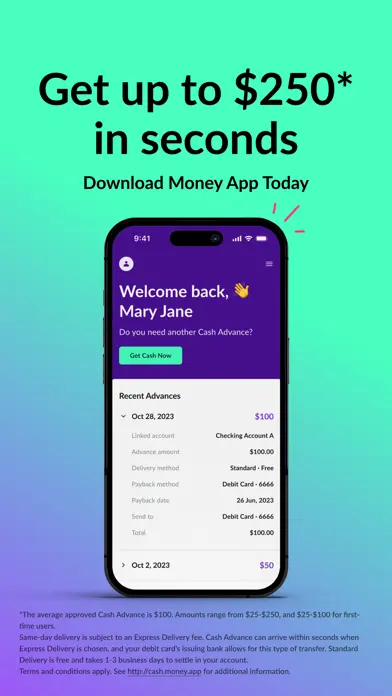
The approval logic is a black box and it’s frustrating. Getting $20 when I clearly had regular income deposits showing felt arbitrary. The app doesn’t explain what banking patterns it’s looking for, so you’re left guessing. Is it my average balance? How often I get paid? It’s a mystery. Then there’s the repayment. The app automatically withdraws the advance plus your tip on your chosen date. I set a $2 tip on my $20, forgetting about it. When the $22 came out of my account the following Friday, it threw my mental math off and nearly caused an issue with a scheduled bill payment. The ease of the app makes the financial impact feel too casual, which is dangerous.
Pricing
They call it free, but it’s not. The “pay what you think is fair” tip model creates weird pressure. On my $20 for seven days, the suggested tips ranged from $0.50 to $4. I felt guilty choosing the lowest option, like I was cheating a system that was “helping” me. I chose $2, which is a 10% fee for one week. If you annualize that, it’s a sky-high rate. There’s also an optional “Express” fee to get the money even faster, which feels like they’re capitalizing on desperation. The cost isn’t hidden, but the emotional framing makes the true price feel murky and, honestly, expensive for what you get.
Developer Notes
The developer is listed as “Line – A Public Benefit Corporation.” That wording made me initially trust them more. A company saying it’s for public benefit should, in theory, prioritize user welfare over profit. My experience didn’t fully align with that ideal. The low advance amounts and the tipping pressure felt designed to extract value from users in a vulnerable spot, even if the mechanism is softer than a traditional payday loan. The “benefit” seemed more theoretical than practical in my specific situation.
Security & Privacy
This is where I get nervous. Using Plaid is standard, but granting an app continuous read access to my transaction history gives me pause. What are they doing with that data? Are they building a profile? Their privacy policy mentions using data for “service improvement” and “personalization,” which are broad terms that often mask tracking and sharing. For a financial app, that level of ongoing access feels excessive just to determine if I’m good for a $20 loan. I revoked the connection through my bank’s portal immediately after my test. The security during transmission seems solid, but the data retention and usage policies are a significant concern for anyone who values financial privacy.
How quickly will I receive a cash advance from Beem?
If approved, the funds are delivered very quickly. In testing, a $20 advance arrived in the user's linked bank account in under two minutes.
Does Beem perform a hard credit check when I apply for an advance?
No, Beem does not perform a hard credit pull. This helps protect your credit score, which is a key benefit of the service.
Why was my approved cash advance amount so low?
The advance amount is determined by an automated review of your banking activity, but the specific criteria are not disclosed. Users report receiving small amounts like $20 even with regular income deposits, which can feel arbitrary.
What should I know about repayment and tipping?
Beem automatically withdraws the advance plus your chosen tip on your selected date. Be mindful of this automatic withdrawal, as it can disrupt your account balance and nearly cause missed payments if not planned for.
How does Beem's cost compare to a traditional payday loan or credit card?
While Beem has no mandatory fee, its 'pay-what-you-think-is-fair' tip model can lead to high effective rates. A $2 tip on a $20 advance for one week annualizes to a very high percentage rate, which may be less transparent than a credit card's APR or a payday loan's fixed fee.